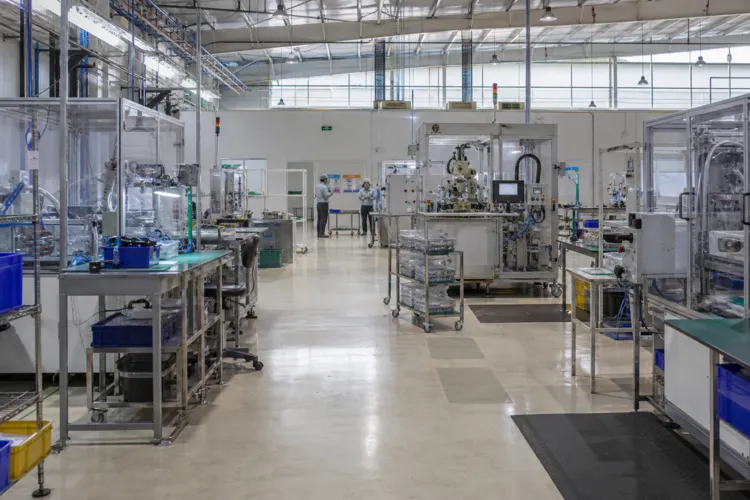
Talk of a Medical Device Manufacturing Zone Indonesia strategy lands at a moment when the domestic market outlook is expanding fast and supply dynamics are changing. One market forecast values the Indonesia medical devices market at USD 61.71 billion in 2024 and projects USD 111.38 billion by 2032, with a CAGR of 7.97% from 2025 to 2032. That kind of trajectory increases the urgency to localize parts of the value chain, especially as demand broadens across applications and end users. In the same forecast, “Diagnostic” is the largest application segment in 2024 at USD 55.81 billion, while “Homecare Settings” is listed as the fastest-growing end-user segment with a 10.87% CAGR from 2024 to 2032.
Import dependence is still a key reality, and it helps explain why manufacturing-zone policy signals matter to regional supply. Despite protectionist measures aimed at boosting local manufacture, imported products account for just over 53% in value terms at about USD 1.5 billion in 2019, with China holding 20% share and Germany 15% according to Fitch Solutions (as cited). Meanwhile, domestic manufacture is described as focusing on lower-value devices such as surgical gloves, bandages, orthopedic aids, and hospital furniture. That split—high import reliance alongside a more basic local output profile—creates a clear incentive to build capabilities that can serve more complex, higher-value categories over time.
Why Testing, Registration, and Materials Matter to Supply Chains
Supply shifts do not come only from factory footprints; they also come from the supporting ecosystem that makes production scalable. Indonesia had over 21,000 medical devices and IVDs registered at the end of 2020, plus over 6,000 household health supply devices. Registration volume is also high: between 1,200 and 2,200 additional medical devices are being registered each month, along with 200 to 800 household health products. On the testing side, Indonesia’s medical device testing services market generated USD 158.6 million in 2025 and is projected to reach USD 346.2 million by 2033, with a 10.26% CAGR from 2026 to 2033. Biocompatibility testing services was the largest segment, with a 51.2% revenue share in 2025.
Demand signals from trade data show why supply chains may be reshaped around surgical and procedure-driven categories. One report describes a 2024 import-market reset driven by elective and high-acuity procedures, and it highlights that the most explosive growth sectors in 2024 were Orthopedic (+552.8%), Dental (+186.4%), and General & Plastic Surgery (+102.9%). It also states General & Plastic Surgery is the market’s largest segment by far, valued at USD 1.36 billion, while Greater China remains the largest supplier at USD 807.4 million in 2024. The same report notes imports from Mexico grew +468.4% and imports from Ireland rose +185.8%, indicating supplier diversification alongside category shifts.
Manufacturing capability also depends on inputs, and materials adoption is another hint of deeper industrial change. One outlook states Indonesia’s pharmaceutical and medical device manufacturers are increasingly incorporating elastomeric materials, and it cites an 8.9% CAGR through 2029 for Indonesia’s medical elastomer market. The same source links elastomer demand to growing healthcare infrastructure and rising medical device manufacturing activity, and it frames Indonesia’s geographic position and growing manufacturing capabilities as supportive of a regional supply role. Put together, faster growth in testing services, sustained registration flow, and expanding materials usage reinforce why a dedicated zone narrative can be read as a signal: Indonesia is not only consuming more devices, it is also building more of the enabling capacity that regional supply chains rely on.
What does a Medical Device Manufacturing Zone Indonesia approach signal for regional supply?
How reliant is Indonesia on imported medical devices?
Which segments are highlighted as large or fast-growing in Indonesia’s medical devices market outlook?
What categories drove the 2024 import-market shift mentioned in the sources?
What do the sources say about medical device registration and testing capacity in Indonesia?